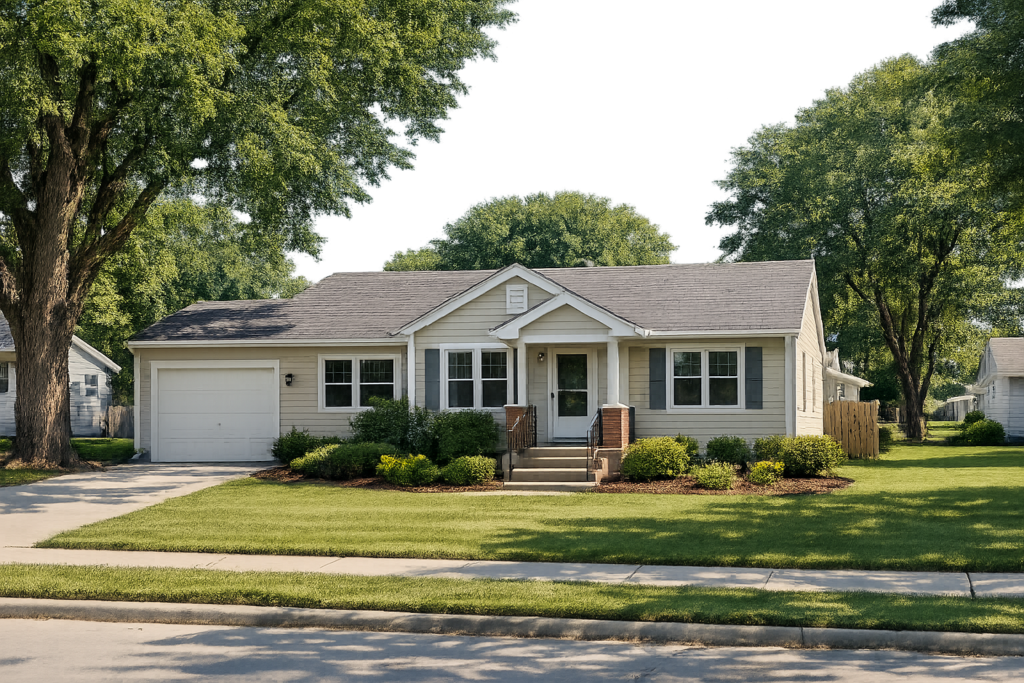
The Greater Des Moines metro posted a median home sale price of $319,000 in June, up roughly 5% from a year earlier. If your SDIRA is funding a note through LGL Co-Lending Fund I, that number isn’t a talking point. It’s the collateral behind your subscription getting stronger in real time. A first-lien mortgage investment is only as good as the property standing behind it, and every property behind an LGL note sits inside a market that just set a new price record. SDIRA investors ask a version of this question early: what actually secures the note my retirement account is funding? The answer starts with the same first-lien claim on Iowa real estate that’s been steady in the fund since day one, and it’s worth walking through what that means now that the local market has moved.
Iowa Real Estate Investing Inside an SDIRA: Why the Collateral Number Matters More Than the Return Number
Most private lending content leads with the return figure. That’s the wrong number to fixate on if you’re funding a note with retirement dollars. The return is what the fund pays you. The collateral is what stands behind the note if a loan needs to be worked out. For SDIRA investors, who are trusting a custodian and a Buy Direction Letter with money they can’t easily touch again until retirement, the collateral question deserves more attention than it usually gets.
Every LGL Co-Lending Fund I note carries first lien on real Iowa property. Not a slice of a national pool of corporate credit or consumer paper. A specific house, in a specific metro, that I can drive to. When that metro’s home values move up, the loan-to-value math behind every note in that market improves along with it.
What the $319,000 Median Actually Signals
A rising median sale price doesn’t mean every property is worth more overnight, and it isn’t a return promise. What it does signal is buyer demand holding up in the market where LGL’s collateral sits. Loans underwritten at conservative loan-to-value ratios against a market with rising prices carry a wider equity cushion than the same loans would in a flat or declining market.
This is Iowa-specific evidence, not a national statistic borrowed from a market LGL doesn’t lend in. Des Moines metro price data is the number that actually matters to a note secured by Des Moines metro real estate, which is the whole point of lending in one market instead of chasing volume across the country.
How Your SDIRA Actually Funds a First-Lien Iowa Note
Most SDIRA investors reading this have already opened the account and moved funds. For anyone confirming the mechanics before funding an LGL note, the process runs in a straight line:
- Open or confirm the self-directed IRA with an approved custodian. Most custodians can open an account in 3-5 business days.
- Fund the SDIRA through a rollover or transfer. A rollover from a 401(k) or traditional IRA typically takes 5-10 business days once paperwork is complete.
- Submit a Buy Direction Letter naming LGL Co-Lending Fund I, the amount, and the terms. LGL provides the subscription documents; the custodian reviews and processes them.
- The custodian conducts its own review, typically 3-7 business days, then wires funds directly from the SDIRA to LGL. The investment is titled in the SDIRA’s name, not yours personally.
Quarterly interest distributions are paid back to the custodian account, not to you directly. That preserves the tax wrapper, whether the account is a Traditional SDIRA deferring tax until distribution or a Roth SDIRA growing tax-free after qualification.
Where UBIT and UDFI Fit In
This is the question SDIRA investors ask before they ask about returns, and it’s fair to ask it before a rising local market makes the collateral conversation more interesting. For most LGL investors, the subscription is funded from existing SDIRA cash, not a non-recourse loan. Interest income from non-leveraged private notes generally falls under the passive-income exclusion from UBIT (Unrelated Business Income Tax), so the interest LGL Co-Lending Fund I pays typically stays inside the SDIRA and compounds without triggering it.
UDFI (Unrelated Debt-Financed Income) is the concern that applies when an SDIRA uses leverage to fund an investment. If your custodian structure includes a non-recourse loan component, that’s worth a direct conversation with your tax advisor before you fund the subscription. Consult your tax advisor regarding your specific SDIRA situation. This is educational information, not tax guidance for your account.
The Custodians SDIRA Investors Already Know
LGL investors fund positions through a handful of major self-directed custodians: Quest Trust Company, Equity Trust Company, Madison Trust Company, IRA Financial Group, NuView Trust, and Directed IRA. Each has a different fee structure and a different focus, flat-fee pricing at Madison, the checkbook-LLC structure at IRA Financial, fast processing at Directed IRA, and none of them is automatically the right answer for every investor. Your custodian is the one who already holds your account, and switching custodians solely to fund one investment rarely makes sense. If you’re weighing custodians for a new SDIRA, that decision is worth a direct conversation rather than a blog post making the call for you.
Why First-Lien Position Matters More When Collateral Values Are Moving
A rising market cuts both ways if a lender isn’t disciplined about it. Aggressive loan-to-value ratios in a hot market are exactly what gets a lender in trouble when momentum reverses. LGL underwrites conservatively regardless of which direction the local market is moving, first-lien position on every deal, real Iowa property, no exceptions for volume.
As of January 1, 2026, LGL has lent over $23M across Little Guy Loans, its affiliated companies, and IRAs, funding 170+ loans with zero foreclosures. Capital is committed for a defined term, a 12-month liquidity provision on positions from $100,000 to $499,999, and 18 months on positions of $500,000 and above. That structure was built to match the short-term nature of the underlying loans, not to promise SDIRA investors a form of liquidity the collateral can’t actually support.
Who This Fits
This isn’t the right structure for every SDIRA investor, and it’s worth saying plainly rather than letting someone assume otherwise. If you’re chasing the highest possible yield across a spreadsheet of private credit options, LGL Co-Lending Fund I is probably not the number you’re looking for. It’s built for SDIRA investors who want predictable quarterly distributions landing back in the custodian account, first-lien real estate backing they can actually picture and track through public market data, and a fund that underwrites the same way whether Des Moines prices are climbing or holding flat.
FAQ
Does a rising Des Moines home price mean LGL’s returns will increase?
No. The return LGL Co-Lending Fund I pays is set by the fund’s structure, 10% annual return, paid quarterly, not by local home price movement. A rising median sale price strengthens the collateral cushion behind existing loans; it is not a return promise and is not correlated with the fund’s stated return.
Can I fund an LGL note with money already inside my SDIRA?
Yes. Most LGL investors fund their subscription from existing SDIRA cash rather than a new rollover. You’ll still submit a Buy Direction Letter naming LGL Co-Lending Fund I, the amount, and the terms, and your custodian handles the review and wire.
Why does LGL only lend in Iowa instead of diversifying nationally?
A single market means the collateral behind every note can be understood directly, not modeled from a distance. Iowa-specific data, like the Greater Des Moines metro’s June median sale price of $319,000, is the number that actually applies to LGL’s collateral, unlike a national statistic pulled from markets LGL doesn’t lend in.
Will I owe UBIT on the interest income inside my SDIRA?
For most SDIRA investors funding their subscription from existing retirement account cash rather than leverage, UBIT generally does not apply to LGL’s interest income distributions. Consult your tax advisor to confirm this applies to your specific SDIRA structure.
What is the minimum investment for an SDIRA holding LGL Co-Lending Fund I?
The minimum investment is $100,000, the same as a direct-cash subscription. LGL Co-Lending Fund I is offered under Reg D 506(c) to verified accredited investors only.
Past performance does not guarantee future results. Returns are not guaranteed. LGL Co-Lending Fund I is offered under Reg D 506(c) to verified accredited investors only.