Iowa foreclosure filings are up roughly 30% since the fall of 2024, and that’s changing what shows up on the MLS every week. More distressed inventory means more listings that look like a deal on the surface, and more risk of overpaying if your deal analysis real estate Iowa process isn’t tight before you write the offer. I run every property through the same four-step math, no exceptions, no gut calls. A house doesn’t become a deal because the price looks low next to the house down the street. It becomes a deal when the numbers say so. Here’s the process, plus a real Waukee listing that failed the math this year.
The Deal Analysis Process for Iowa Real Estate Investors
Every flip I look at, no matter the neighborhood or price point, comes down to the same math. Rising foreclosure inventory doesn’t change the formula. It changes how many properties I have to run through it before one actually clears.
Four Steps to Analyze Any Iowa Flip
- Pull your comps. Find three to five recently sold, fully renovated homes near the property to build a real ARV, not a guess.
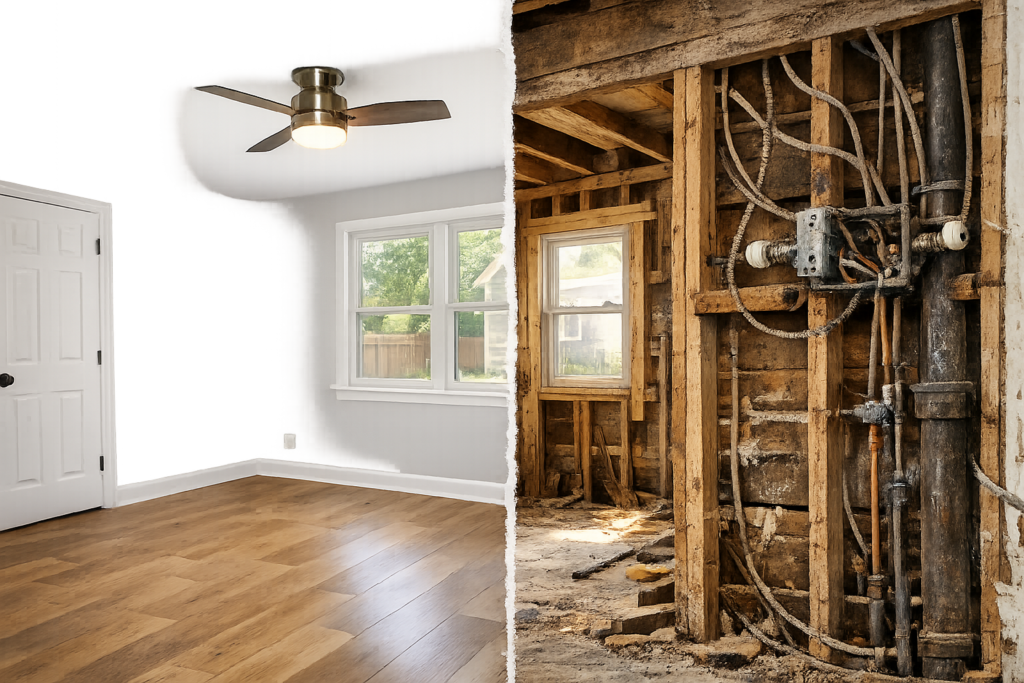
- Walk the property. Note the roof, the electrical panel, the mechanicals, and anything structural before you fall for the finishes.
- Build a rehab number. Price the scope room by room, then add a contingency for what the walk-through didn’t show you.
- Check the 70% rule. Purchase price plus rehab should land at or under 70% of your ARV estimate. If it doesn’t, it isn’t a deal yet.
Step four always comes last. Run it first and you’ll talk yourself into a bad number just because the neighborhood felt right.
A Waukee Listing That Looked Better Than It Was
I ran the numbers on a pre-foreclosure listing in Waukee that came on the market this spring at $210,000. Comps on similar three-bedroom ranches nearby, all sold within four months and fully updated, put ARV close to $305,000. On paper, that’s a wide spread.
Walking the property told a different story. Original 1998 mechanicals, a roof at the end of its life, and a kitchen that needed a full gut. A real rehab estimate landed at $58,000. Seventy percent of $305,000 is $213,500, and the rehab number comes out of that ceiling first. That leaves $155,500 as the most this deal could pay, not the $210,000 asking price. The gap between what a distressed listing looks like it’s worth and what the math actually supports is exactly where rising foreclosure inventory can catch an investor who skips the process.
Where Rising Foreclosure Inventory Changes the Math
More distressed and pre-foreclosure inventory doesn’t make every listing a better deal. It changes a few specific things about how you run the analysis:
- Condition swings wider. Distressed sellers defer maintenance longer, so your rehab contingency needs to grow, not shrink.
- Comps get noisier. A wave of foreclosure sales can drag your ARV comps down if you aren’t filtering for true renovated sales.
- Timelines compress. Pre-foreclosure sellers often need a fast, clean close, which rewards the investor who already knows their numbers cold.
What Funding Looks Like Once the Deal Analysis Checks Out
Once a deal clears the 70% rule, financing shouldn’t be the part that slows you down. Through Little Guy Loans, I fund up to 90% of the purchase price and up to 100% of rehab costs on qualifying Iowa flips, with every loan capped at 70% of ARV, the same ceiling I just used to analyze the deal in the first place.
FAQ
What is real estate deal analysis?
A real estate deal analysis is a repeatable process that turns a property listing into a purchase-price ceiling, using ARV, rehab costs, and the 70% rule to decide what a flip can actually pay.
How has rising foreclosure inventory changed deal analysis in Iowa?
Rising foreclosure inventory is a supply shift that adds more distressed listings to the market, which means wider condition variation and noisier comps, not a shortcut around the same four-step analysis.
How many comps do I need to calculate ARV?
A reliable ARV calculation uses three to five comparable sales from the last three to six months, adjusted for condition and finish level.
What is the 70% rule in fix and flip investing?
The 70% rule is a fix-and-flip guideline stating that purchase price plus rehab costs should not exceed 70% of a property’s after-repair value.
Can I get funding once my deal analysis checks out?
Little Guy Loans funds Iowa flips that clear the 70% rule, up to 90% of purchase price and up to 100% of rehab costs, with every loan capped at 70% of ARV.
Foreclosure inventory is up across Iowa, and that means more listings worth a second look, not more deals you can skip the math on. A rising number of distressed sellers on the market changes the volume of properties worth analyzing. It does not change what makes one of them a real deal. Run the same four steps on every property: pull real comps, walk the house, build an honest rehab number, and let the 70% rule make the final call before you ever write an offer. The investors who get faster at deal analysis real estate Iowa work are the ones who treat every distressed listing as a math problem first and an opportunity second, no matter how good the story behind the listing sounds.