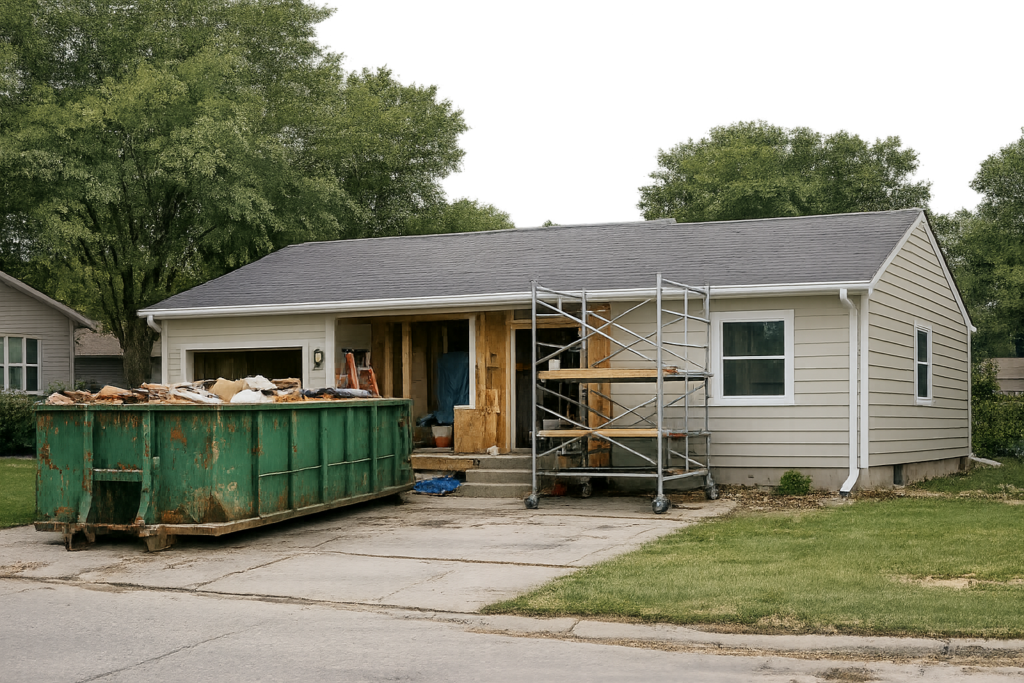
Most first flip mistakes in Iowa don’t show up on the purchase contract. They show up three weeks into the rehab, when the budget is gone and the property still isn’t done. I’ve watched plenty of first-time flippers make the same handful of errors, over and over, on deals that looked solid on paper. The good news is that nearly every one of these mistakes is avoidable if you know where to look before you make an offer. This isn’t a list of things that might go wrong. It’s a list of things that do go wrong, on a predictable schedule, unless you plan around them. Here’s where Iowa investors trip up on their first flip, and what to do instead.
First Flip Mistakes Iowa Investors Should Avoid
I see the same five mistakes on nearly every first flip that runs into trouble. None of them are exotic. They’re basic planning gaps that feel small going in and turn expensive coming out.
- Underestimating the rehab budget. The number on the spreadsheet and the number the house actually needs are rarely the same.
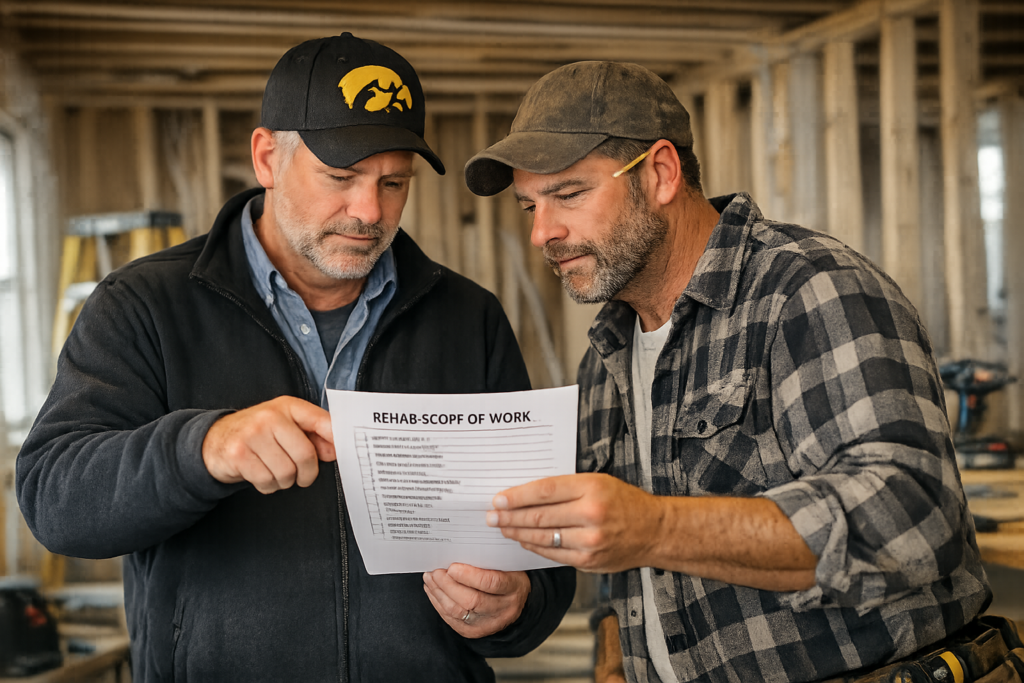
- Skipping a real scope of work. A verbal agreement with a contractor isn’t a plan. It’s a guess with a handshake attached.
- Financing the deal wrong from the start. Not knowing what a lender will actually fund can stall a deal before it starts.
- Ignoring holding costs. Every extra month on a flip costs money even when no work is happening.
- Buying without an exit plan. A flip with no backup plan is a bet that the market won’t move before you sell.
Why the Rehab Budget Trips Up First-Time Flippers
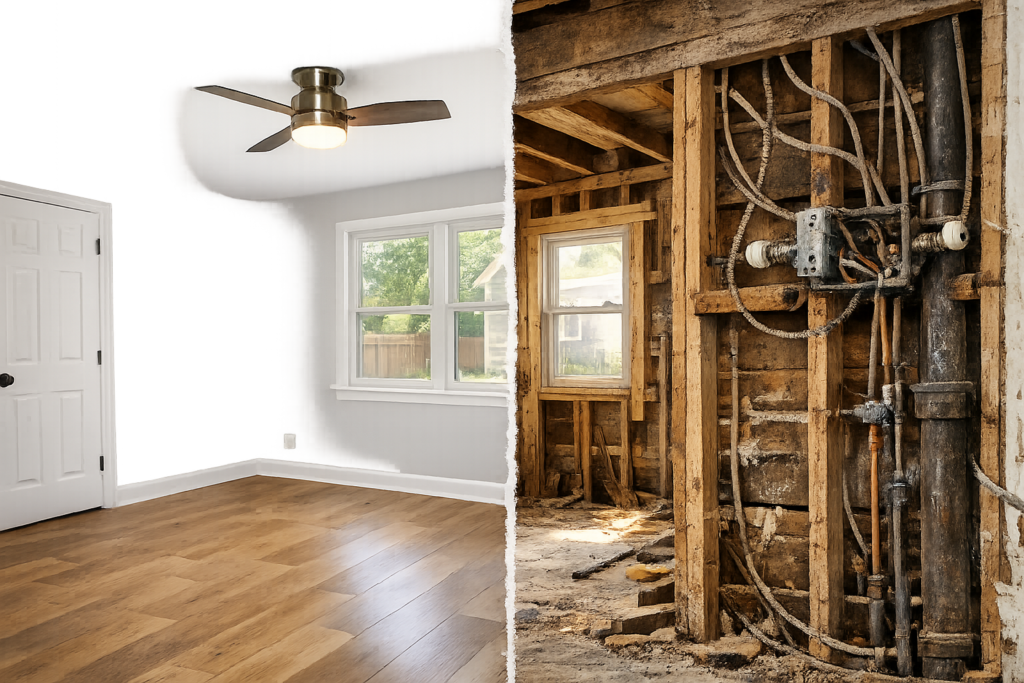
Rehab budgets go wrong for a simple reason: first-time flippers price the house they can see, not the house that’s actually there. A house in Norwalk with original 1970s plumbing might look like a cosmetic flip from the listing photos. Pull the vanity and find galvanized pipe running through the whole place, and the budget changes fast.
Build in a contingency before you ever submit an offer, not after the first change order shows up. Ten to fifteen percent of the rehab budget set aside for surprises is standard, and on an older property in an established Des Moines metro neighborhood, it isn’t optional.
A written scope of work protects you here too. A scope of work fix and flip document lists every task, material, and cost line by line, so “finish the basement” isn’t left open to interpretation between you and the contractor.
Getting Your Financing Structure Right From Day One
The second mistake compounds the first. Flippers who don’t understand how a hard money loan is structured often assume they need more cash up front than they actually do, or they find out mid-deal that their lender won’t cover a cost they were counting on.
Know how much of the purchase price and rehab a loan can actually cover before you write an offer, not after. That single piece of information changes how aggressively you can bid and how much of your own cash you need to hold in reserve.
It also affects your exit math. A flip that pencils out at a healthy margin on paper can shrink fast if financing costs and holding costs weren’t part of the original plan for making money flipping houses in Iowa.
FAQ
What is the most common mistake first-time flippers make in Iowa?
The most common first flip mistake in Iowa is underestimating the rehab budget. A rehab budget shortfall is a gap between what a flipper planned to spend and what the property actually needs, and it’s the fastest way to turn a profitable deal into a break-even one.
How much can a first-time flipper borrow on an Iowa deal?
A hard money loan on an Iowa flip is a short-term loan that can fund up to 90% of the purchase price and up to 100% of rehab costs, with the total amount capped at 70% of the after repair value.
Do I need an exit plan before I buy my first flip?
A flip exit plan is a decision made before closing about whether a property will be sold or held as a rental if the market shifts. Buying without one means gambling that conditions stay the same for the entire project.
What Little Guy Loans Covers on Your First Iowa Flip
Financing is worth understanding in plain terms before you start shopping for a deal. On a qualifying flip, funding can cover up to 90% of the purchase price and up to 100% of the rehab budget. The total loan amount is capped at 70% of the after repair value, and that 70% ARV number is the controlling limit. It decides how big the loan actually gets, regardless of what the 90% and 100% numbers suggest on their own.
Knowing that cap before you make an offer changes how you structure a deal. It tells you how much of your own cash needs to be in the transaction, and it keeps your rehab budget honest instead of hopeful.
None of these first flip mistakes are complicated once you know to watch for them. A realistic rehab budget, a written scope of work, a clear understanding of what your financing actually covers, honest holding-cost math, and an exit plan before you buy: that’s the difference between a first flip that builds momentum and one that just breaks even. Iowa’s flip market rewards investors who plan for the boring stuff before it becomes the expensive stuff. Build the habit on this deal, and the next one gets easier.